
What's Really Happening in Carroll County's Housing Market?
What's Really Happening in Carroll County's Housing Market?
By Jessica Sauls | Realtor & Owner, Memory Lane Property Group | October 21, 2026
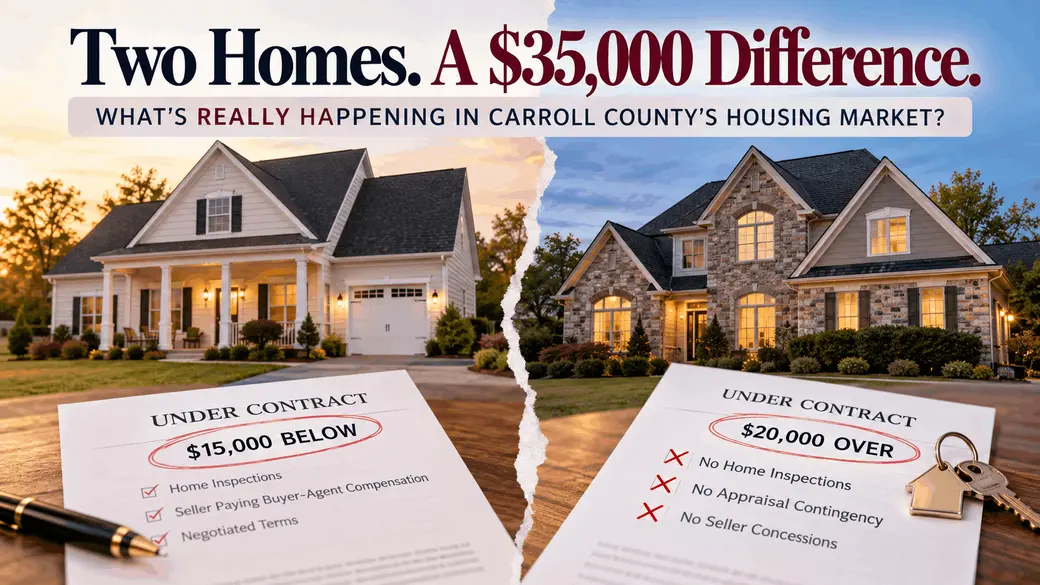
I shared something in my Monday morning newsletter that I think deserves a deeper conversation. I recently put two homes under contract in roughly the same $350,000–$400,000 price range.
One went under contract for $15,000 below asking price, with home inspections and the seller agreeing to pay the buyer-agent compensation. The other went under contract for $20,000 OVER asking price, with no home inspections and no appraisal contingency.
That's a $35,000 difference in how the two offers compared with their respective asking prices and two very different sets of contract terms Same general price range. Same local market. Very different outcomes.
So, what is happening?
After more than two decades of helping people buy and sell homes across Carroll County, Central Maryland and Pennsylvania, here's what I'm seeing: We're experiencing what feels like two completely different housing markets at the same time.
And if you're thinking about buying or selling, understanding the difference could save you a tremendous amount of frustration and potentially thousands of dollars.
Are Maryland Home Prices Actually Falling?
Let's start with what the local numbers tell us. According to Bright MLS, the median sold price in Carroll County during September 2026 was $474,350, up 2.6% from September 2025. Year to date, the median sold price was $480,000, compared with $460,000 during the same period in 2025.
So no. The countywide figures don't show that Carroll County home prices are collapsing.
But here's where things get interesting.
During September:
| Carroll County Market Indicator | September 2026 |
|---|---|
| Median sold price | $474,350 |
| Active homes for sale | 366 |
| New pending sales | 156 |
| Closed sales | 151 |
| Average days on market | 34 |
| Average sold-to-original-list-price ratio | 98.7% |
| Months of housing supply | Approximately 2.2 |
Exactly one year ago, Carroll County had 324 active listings, and the average days on market was 26.
Home prices can be holding steady or even increasing while sellers lose some of their negotiating power. Those two things are not mutually exclusive. And that's exactly why I don't believe you can base this market by looking at median prices alone. The numbers tell a story, but it's only part of the story.
48 Price Reductions in Just Seven Days
Here's what really caught my attention while reviewing Bright MLS on October 17.
In one seven-day period, Carroll County recorded:
-
48 price decreases
-
34 new active listings
-
23 properties moving into Active Under Contract or Pending status
In other words, more existing listings reduced their asking prices than the number of new homes that came on the market that week.
Now, I don't want anyone drawing conclusions about an entire housing market based on seven days of activity. The market has ebbs and flows. Buyers are adjusting to the new interest rates, and the homes they were seeing 3 weeks ago look a lot different than the homes they are seeing now.
But this is exactly the kind of activity I'm watching because it tells us something about what's happening right now, rather than only what closed last month. Sellers are adjusting. Buyers are being selective. And let's be honest, Buyers have really been through a lot over the last 6 years. And the expectations many of us developed during the frenzied housing market of the past several years aren't necessarily matching today's reality.
Why Are Some Homes Still Getting Multiple Offers?
This is where I think the conversation becomes especially interesting. I'm still seeing beautifully maintained, thoughtfully updated, and truly unique homes attract tremendous attention. A gorgeous property on five acres, an immaculate home with a distinctive design, or a house that requires virtually no work can still have buyers competing for it.
Why?
Because those properties are hard to find. It's not that they don't exist, it's that many homeowners don't need to move, have no mortgage or a very low rate and aren't motivated to move. It's been that way for several years now, creating an inventory shortage that we simply haven't seen before.
Now imagine you're selling a fairly typical home in a neighborhood where buyers have four or five similar options. One has fresh paint, beautiful landscaping, updated fixtures, and is spotless. Another has clutter in every room, worn finishes, overgrown landscaping, and a list of projects waiting for the next owner.
If they're priced similarly, which one do you think a buyer is going to choose?
That doesn't mean the second home can't sell. It means the price, preparation, and marketing strategy must reflect how buyers actually see the property.
In a market where buyers have choices, presentation isn't just about making a house look pretty. It's about making your home stand out from the competition.
Why Mortgage Rates Matter More Than Many Sellers Realize
Here's another piece of the puzzle.
According to Freddie Mac, the average 30-year fixed mortgage rate reached 7.40% on October 15, 2026. Higher rates directly affect what buyers can afford.
Consider a buyer purchasing a $450,000 home with 20% down. At a 6.76% mortgage rate, the principal-and-interest payment on a $360,000 loan would be approximately $2,337 per month. At 7.40%, that same mortgage payment increases to approximately $2,493 per month.
That's roughly $156 more every month for the exact same house, before property taxes, homeowners insurance, or HOA fees.
Now imagine being a buyer who spent months shopping for a $600,000 house. You know exactly what you want. You've toured homes, researched neighborhoods, and imagined where your furniture will go. Then your lender tells you that your comfortable price range has dropped. Your buying power changed. But your expectations may not have changed nearly as quickly.
That kind of Buyer frustration has many Buyers pumping the breaks. Especially our Buyers in the $550,000 and below price range.
When I make my Monday morning calls, I call listings in the same area as my listings. I'm asking the other agents very specific questions, like "how many showings did you have this week?", "Did you host an open house?" "What's traffic been like for you?". In areas where the listings are priced under $550,000, agents aren't seeing a lot of traffic, if any at all.
When interest rates rise, we tend to see buyers pull back for a few weeks. There's an adjustment period.
The Latest Mortgage Application Numbers Tell Us Something Important
Closed sales are useful, but they tell us what happened after a buyer and seller reached an agreement about 45 days earlier, before the interest rates went up. So the data we're seeing is lagging.
That means a house closing today may have gone under contract when mortgage rates were lower. So I also pay attention to mortgage applications because they give us a more immediate view of financing demand.
According to the Mortgage Bankers Association's October 21 report, purchase mortgage applications fell 7% during the week ending October 16 and were 18% below the same week in 2025.
Those are national figures, not Carroll County-specific numbers, but they're important context. They suggest that higher borrowing costs are weighing on buyer activity. And that helps explain why the experience of a seller whose home went under contract in August may be very different from someone listing their home in October.
Buyers Are Negotiating Again, Even When They Pay Asking Price
Something else I find interesting is how much attention people pay to whether a house sold above or below asking price. That's great information, but again, those are just numbers and those numbers are only telling us part of the story.
In my review of 60 Carroll County residential sales between approximately $300,000 and $500,000 that closed during the 30 days ending October 17, 35 included reported seller concessions.
That's about 58%.
Some buyers received help with closing costs or other expenses, while others negotiated different terms. A buyer might offer $10,000 above asking price but request $15,000 in seller-paid closing costs. And the public sales record still shows a home selling $10,000 over asking.
The seller's proceeds tell a more complicated story.
Of course, concession amounts, financing structures, and contract terms vary. Not every concession is equivalent to a straight price reduction. My point is that the headline selling price doesn't tell you everything about the negotiation. That's why I pay attention to inspections, repairs, closing costs, appraisal contingencies, and the terms of the agreement, not simply the final sales price.
Buyers Are Still Thinking Like It's 2022
Now let's talk about something the statistics don't show us with the numbers.
Buyer psychology.
For years, buyers became accustomed to losing homes. They would fall in love with a property, rush to see it, write a competitive offer, and still lose to someone offering more money, fewer contingencies, all cash, a classic car, deer meat...(true story... )
And after going through that repeatedly, for years, it really has taken a toll on Buyers. I'm now seeing Buyers hesitate to schedule showings for weeks because they're tired of the bidding wars. And even that takes a toll on Buyers, I have seen my own listings receive no offers for 2-3 weeks, then multiple offers day 15. One Buyer might not believe we really have multiple offers and comes in lower, while the other offer shines above asking price and wins. That doesn't help with Buyer frustration either. The market is changing, but buyer and seller expectations aren't always changing at the same speed.
What Should Carroll County Sellers Be Doing Differently?
If you're preparing to sell your home, I want you to understand something.
You can't control interest rates, or the economy. You really can't control how many competing homes come on the market.
But here's what you can control, and I cannot stress this enough.
You can clean your home. I cannot tell you how many homes I have shown that have dirty socks on the floor, dirt on every baseboard, airvents that show signs of a struggle. Struggle to breathe that is.
Your home can be dated, that's not what scares most buyers off. In fact, many buyers love a "dated" home. (Myself included)
What buyers aren't loving is a home that hasn't even been maintained or cleaned. If there is ketchup on every surface in muliple rooms or an actual dust lion emerging from under your refrigerator, I'm talking about you. If you have your home on the market for $600,000, you should invest in a new airfilter. I promise you, I will notice and point it out to the Buyers that I am touring with. And no, 23 glade plug-ins will not make your home smell more inviting.
You can pay attention to your landscaping.
You can price your home based on the competition buyers have today, not simply what another house sold for six months ago, because that number from 6 months ago is irrelevant.
And you can make an informed decision about improvements that are worth making before listing.
Not everyone can afford a new roof, HVAC system, or kitchen renovation. I understand that. But almost everyone can pick up the dirty socks before a showing. I wish I was joking, but I'm not. And it's not that buyers can't see beyond the dirt, it's that they don't want to invest in something that hasn't been cared for. Because when buyers have choices, even the "little" things matter.
You don't necessarily need the most expensive house on the street. You need to give buyers a compelling reason to choose yours.
What About Buyers? Is This Finally Your Opportunity?
Potentially, yes. But I wouldn't assume every seller is desperate or that every property is negotiable.
Some homes are still attracting tremendous interest, while others may offer opportunities to negotiate on price, inspections, repairs, seller-paid closing costs, or mortgage-rate buydowns.
The trick is knowing the difference. And sometimes, a buyer who has been searching for months may find a home they love that has been available for several weeks. Instead of automatically assuming something must be wrong with it, it's worth asking questions.
How does its price compare with similar homes? Has the seller already made adjustments? What repairs or updates might be needed? Could there be an opportunity to negotiate terms that make the purchase work?
Those conversations are a lot more productive than assuming every house is either a bidding war or a bargain.
Is the Maryland Housing Market Returning to Normal?
I think that's a possibility worth discussing.
Before the extraordinary housing conditions we experienced beginning in 2020, buyers and sellers routinely negotiated inspections, repairs, financing contingencies, and closing costs.
Homes didn't always sell in 3 or 4 days. Sometimes they took 45- 90 days. We considered that a balanced and healthy market and didn't think anything was necessarily wrong.
Buyers and Sellers would negotiate, come up with terms that worked for everyone and both parties walked away from settlement feeling good about the transaction. Healthy!
Carroll County's inventory remains relatively limited by historical standards, so I'm not ready to declare that we've returned to a fully balanced market. But I do believe we're moving away from an environment where sellers could assume they held nearly all the cards.
I also want to point out that over 29% of Maryland Homeowners have no mortgage at all. And Nationally, 49.1% of homeowners have a mortgage rate under 4%. That's not giving a lot of Maryland Homeowners incentive to move, so inventory might remain low. And if you're expecting another forclosure crisis, it's hard to believe that we will with numbers like those.
My Takeaway: There Isn't Just One Housing Market
At the end of the day, people still have to move. Families grow, people downsize, people get deployed, people pass on and people relocate. People need to move, and when it's time to move, buying/selling may be your best option.
Some would say that Buyers are being more selective, I would say that Buyers want a fair price for their investment and they're not willing to overlook all of the "little" things anymore.
A unique, beautifully presented home may still attract multiple offers and excellent terms and a home with several comparable alternatives may need sharper pricing, better preparation, or more flexible negotiating terms.
And a buyer who felt powerless a year or two ago may now have opportunities that weren't available before.
This is exactly why I love having these conversations.
If you're thinking about buying or selling, give me a call.
I'm looking forward to learning more about your goals and helping you understand what the market really looks like for you.
Jess Sauls
Realtor & Owner | Memory Lane Property Group
443-983-0402
www.memorylanepropertygroup.rocks
Market Data & Sources
-
Bright MLS / ShowingTime: Carroll County September 2026 Local Market Insight, reported October 8, 2026.
-
Bright MLS: Carroll County seven-day market activity and residential listing reports, October 17, 2026.
-
Freddie Mac: Primary Mortgage Market Survey, October 15, 2026.
-
Mortgage Bankers Association: Weekly Mortgage Applications Survey, October 21, 2026.
Local figures reflect the reporting periods indicated. National mortgage statistics provide broader context and do not necessarily reflect identical conditions in Carroll County. Contract-specific examples reflect firsthand experience; individual results vary.
Categories
Recent Posts
I'm Jessica Sauls, and I help Buyers and Sellers navigate their Real Estate needs in Carroll County, Maryland and surrounding areas.
It's my Mission to provide strategic, ethical, and compassionate real estate guidance that empowers people to build stability, wealth, and a life they love. We create calm, clear, and trustworthy experiences, and we strengthen our community through service, connection, and integrity.
I believe in building futures, relationships, and legacies that last.